
It’s hard to let go of a 3% mortgage rate. There’s no question about it. It’s the main reason why many homeowners in Chicago, Illinois, and across the country have delayed moving in recent years. But here’s something to consider.
While your low mortgage rate might be comfortable, it doesn’t make up for being cramped, having stairs your knees can’t handle, or living miles away from family. Real-life needs consistently push sellers off the fence, regardless of where mortgage rates sit.
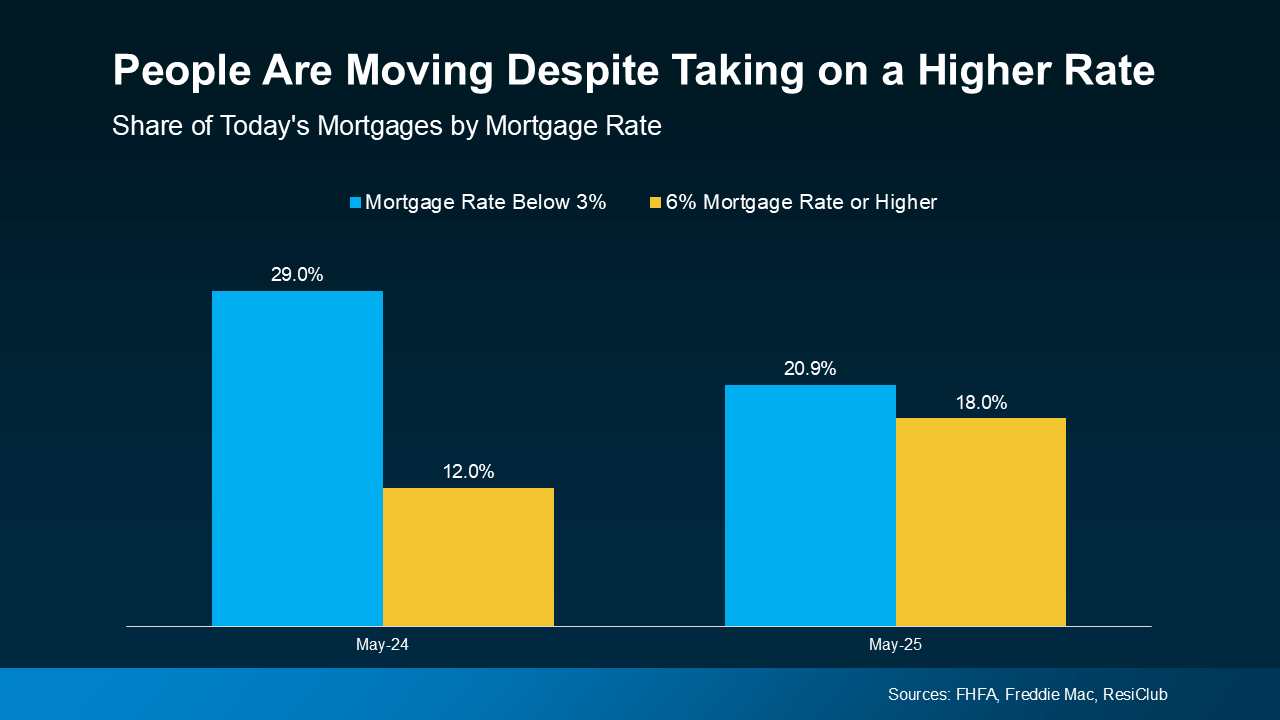
Recent housing data from Freddie Mac shows the share of homeowners holding mortgage rates below 3% continues to drop as life changes demand relocation. Consequently, more homeowners are comfortably taking on current market mortgage rates to secure the right home.
How Changing Mortgage Rates Impact Chicago Home Sellers
Why are homeowners across Chicago neighborhoods willing to trade their ultra-low rates? A national seller study by Realtor.com revealed that nearly 80% of active sellers move out of personal necessity rather than market timing. The top drivers include:
- Needing More Space: Welcoming a new child, setting up dedicated work-from-home offices, or hosting aging parents in two-flat and single-family layouts.
- Downsizing for Simplicity: The kids have moved out, and maintaining a large home is exhausting. Downsizing cuts utility bills, maintenance overhead, and property taxes.
- Closer to Family: Relocating across town or near Chicago suburbs like Oak Park or Evanston to be near grandchildren or support older family members.
- Major Life & Career Changes: Job relocations, remote-work transitions, marriage, or divorce frequently require a fresh residential start.
Why Builders Compete on Mortgage Rates and Buyer Payments
Once you decide to sell, elevated mortgage rates introduce another variable: buyer affordability. Today’s buyers calculate every purchase down to the monthly payment, especially when factoring in Cook County property taxes.
In many suburban and outlying areas, homebuilders are actively winning over buyers by offering upfront incentives. According to data reported by HousingWire, new-home sales have held steady because builders frequently offer mortgage rate buydowns, which temporarily or permanently lower the buyer’s interest rate and monthly payments.

Navigating Shifting Mortgage Rates as an Existing Chicago Home Seller
You don’t need to be a large corporation or builder to attract motivated buyers in a higher-rate climate. Resale homes in Chicago offer distinct advantages that new suburban tract homes cannot replicate:
- Unmatched Neighborhood Amenities: Chicago’s established communities—from Bronzeville and Hyde Park to the South Loop and Beverly—offer walkability, historic architecture, public transit, and vibrant cultural hubs that outlying new builds lack.
- Seller-Paid Rate Buydowns: Sellers can offer closing concessions that fund a 2-1 or 1-0 mortgage rate buydown for the buyer. This lowers the buyer’s initial monthly payments without requiring you to make massive cuts to your headline sales price. Learn more about offering buyer closing cost concessions.
- Strategic Initial Pricing: In an affordability-focused market, overpricing leads to immediate stagnation. Pricing accurately against recent neighborhood comps sparks immediate interest. Explore our guide on pricing your house right in today’s market.
Planning Your Chicago Home Sale in Today’s Rate Environment
A low mortgage rate is great on paper, but it cannot fix a home that no longer matches your lifestyle. At the same time, navigating current mortgage rates requires smart positioning and an understanding of what buyers need to make their monthly budget work.
If you are ready to explore your options, connect with our licensed real estate agents in Chicago, IL for a custom equity review and strategic pricing consultation.